Options
Record options volume leaves the hedging question open
Same-day SPX options averaged 3.2 million daily contracts in the third quarter. Their effect on the underlying market depends on dealers’ net positions and how those positions change.
The LME is extending warehouse charge-cap freezes through March 2032. Withdrawal costs and access still determine how an exchange price translates into delivered metal.
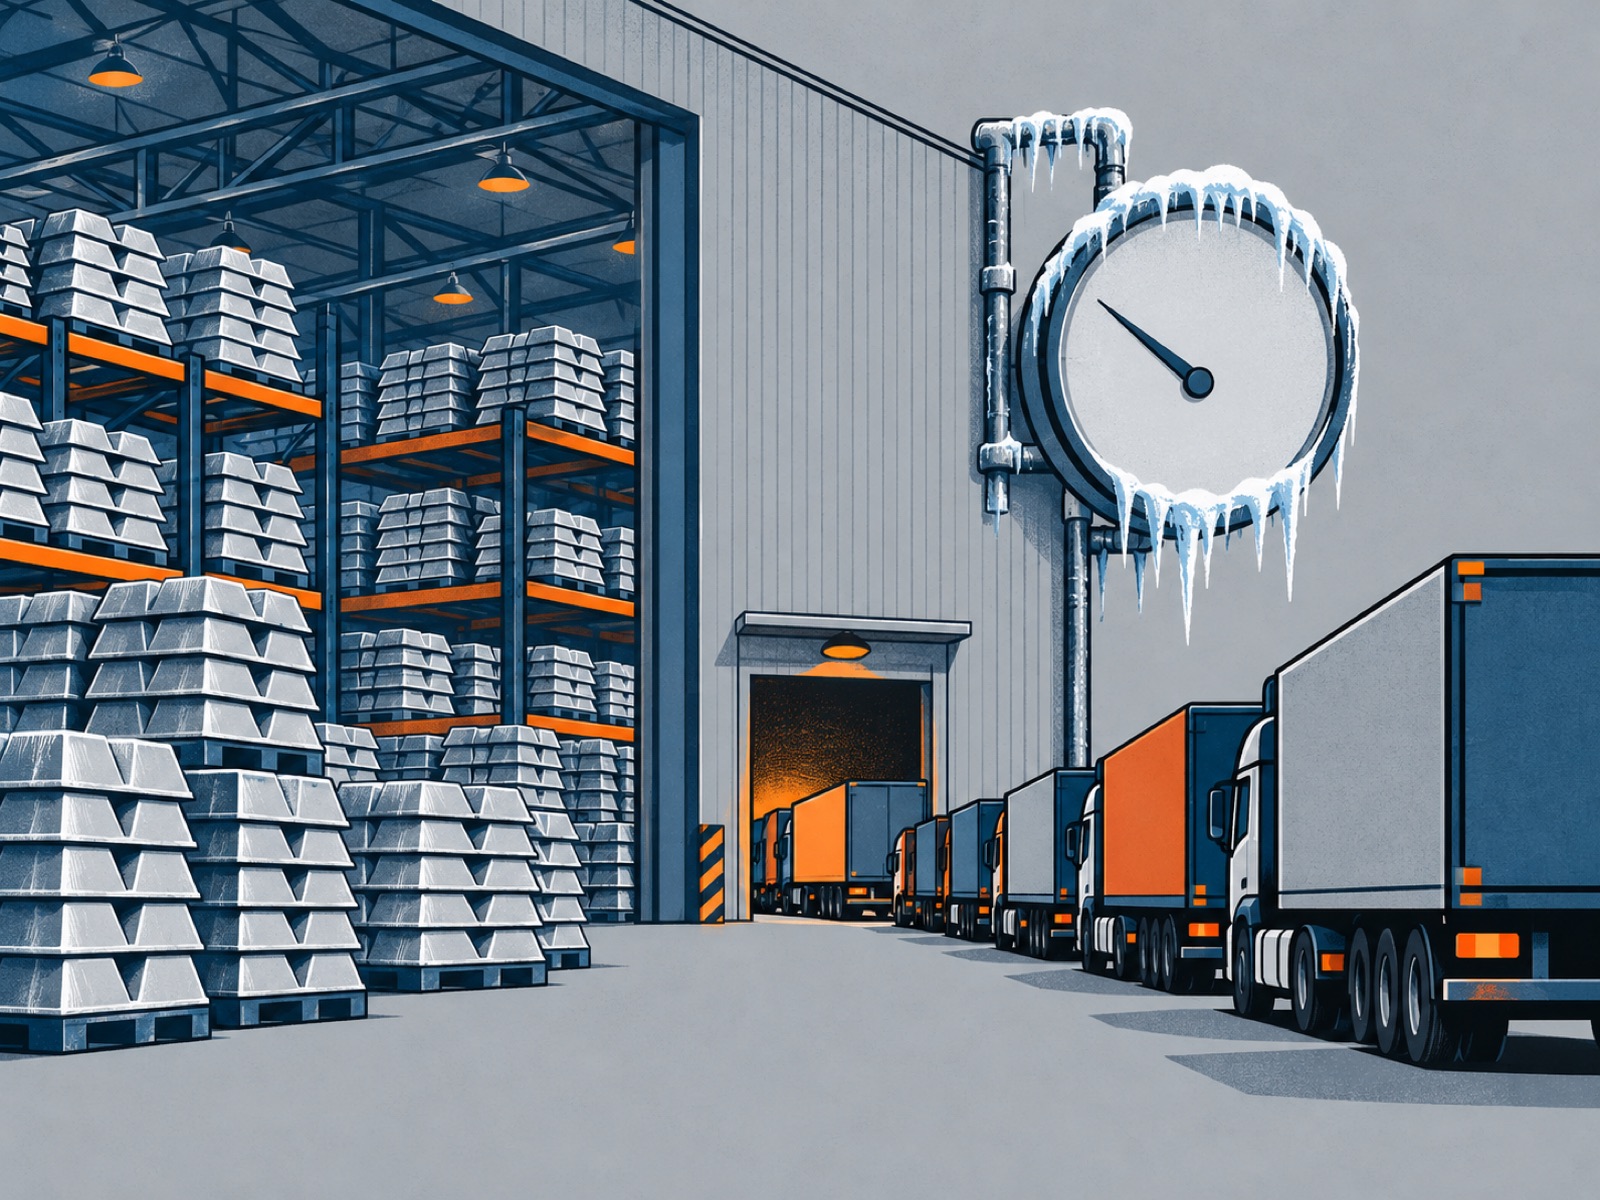
A tonne of metal in a warehouse and a tonne at a factory gate are different economic propositions. Rent, loading charges, transport and waiting time sit between them. The London Metal Exchange’s latest warehouse changes address these costs of physical delivery. Its July decision schedules amendments to the warehouse agreement for October 30, 2026, and extends the freeze on rent and Free on Truck charge caps through March 31, 2032. The timetable is set out in the decision notice.
The freeze changes the terms on which existing metal can be held and withdrawn. By making part of the delivery bill more predictable, it can affect the price gap needed for a trader to move metal between the exchange network and a physical customer.
An LME warrant represents entitlement to a specific lot of approved metal. Owning the document and receiving metal at a chosen destination are separate stages. A buyer still has to understand where the lot is, what it costs to remove and how long the journey takes.
The exchange describes delivery through approved warehouses as an anchor for price convergence. If exchange prices move sufficiently above physical prices, an arbitrageur can buy suitable metal and deliver it against an exchange sale. In the other direction, obtaining exchange metal can help meet physical demand. Those possibilities connect the financial contract to an industrial material.
A price gap must be large enough to cover the relevant handling, financing and transport costs before a trade is attractive. Uncertain withdrawal costs make that calculation harder. Predictable terms can therefore improve the credibility of the delivery mechanism even when few market participants actually take delivery.
A published maximum leaves room for individually negotiated charges below it. Freight prices and the cost of financing inventory also remain outside a rent cap. The effect on a customer’s total bill therefore depends on its existing terms, the services it uses and the journey the metal must make.
The detailed decision also sets a US$10-per-tonne re-warranting cap for the 2027/28 charge year, subject to the annual challenge process. Its notice requirement is narrower than a rule for every fee increase: warehouses must give at least three months’ notice of increases of 20% or more for free-on-rail, free-alongside, free-in-container-yard and slot-rescheduling services. These rules address the risk that an apparently attractive headline charge is undermined by the cost of another necessary service. A customer comparing warehouses needs to account for each service required to withdraw the metal.
Warehouse operators face the other side of the cap freeze. Some consultation respondents warned that rising costs could discourage participation under frozen caps; the exchange disagreed that the caps made the change inappropriate. The disagreement concerns whether the permitted charges will sustain participation as operators’ costs change. The decision itself supplies no evidence of a subsequent capacity shortage or reduction in customer bills.
Physical warehouses possess commercially useful information about stock movements. The reform extends information-barrier and auditing requirements to non-related warehouse companies. Their barriers must operate from January 1, 2027; the first audit covers that calendar year, with its report due by April 30, 2028. Equal treatment across operators is important because confidence in the storage network also depends on what happens to information generated inside it.
Public stock reports address a separate question: what metal is available and where. The LME’s warehouse and queue reports distinguish stocks by operator and location, deliveries during the month, and waiting times at the month’s final business day. An aggregate stock figure cannot answer every question about immediate availability. Metal may exist in an inconvenient location, and a waiting-time observation describes a particular reporting date.
For a factory buying exchange metal, the relevant comparison remains the full delivered cost: the price of the warrant, storage and withdrawal charges, finance, transport and any wait. The cap freeze makes some of those terms more predictable. Whether it improves access will depend on warehouses continuing to offer the capacity and services needed to turn a warrant into a timely delivery.
Same-day SPX options averaged 3.2 million daily contracts in the third quarter. Their effect on the underlying market depends on dealers’ net positions and how those positions change.
USDA expects more cotton at the end of 2026/27 than it did a month ago. The stockpile would still shrink over the season, with Brazil projected to outship the United States.
The second US-index reconstitution of 2026 takes effect after the December 11 close. Ranking, initial membership lists and implementation create different trading decisions.