Options
Record options volume leaves the hedging question open
Same-day SPX options averaged 3.2 million daily contracts in the third quarter. Their effect on the underlying market depends on dealers’ net positions and how those positions change.
EEX’s top-to-bottom contracts measure the gap between expensive and cheap power periods. Their price-only formula leaves storage operators with a mismatch to manage.
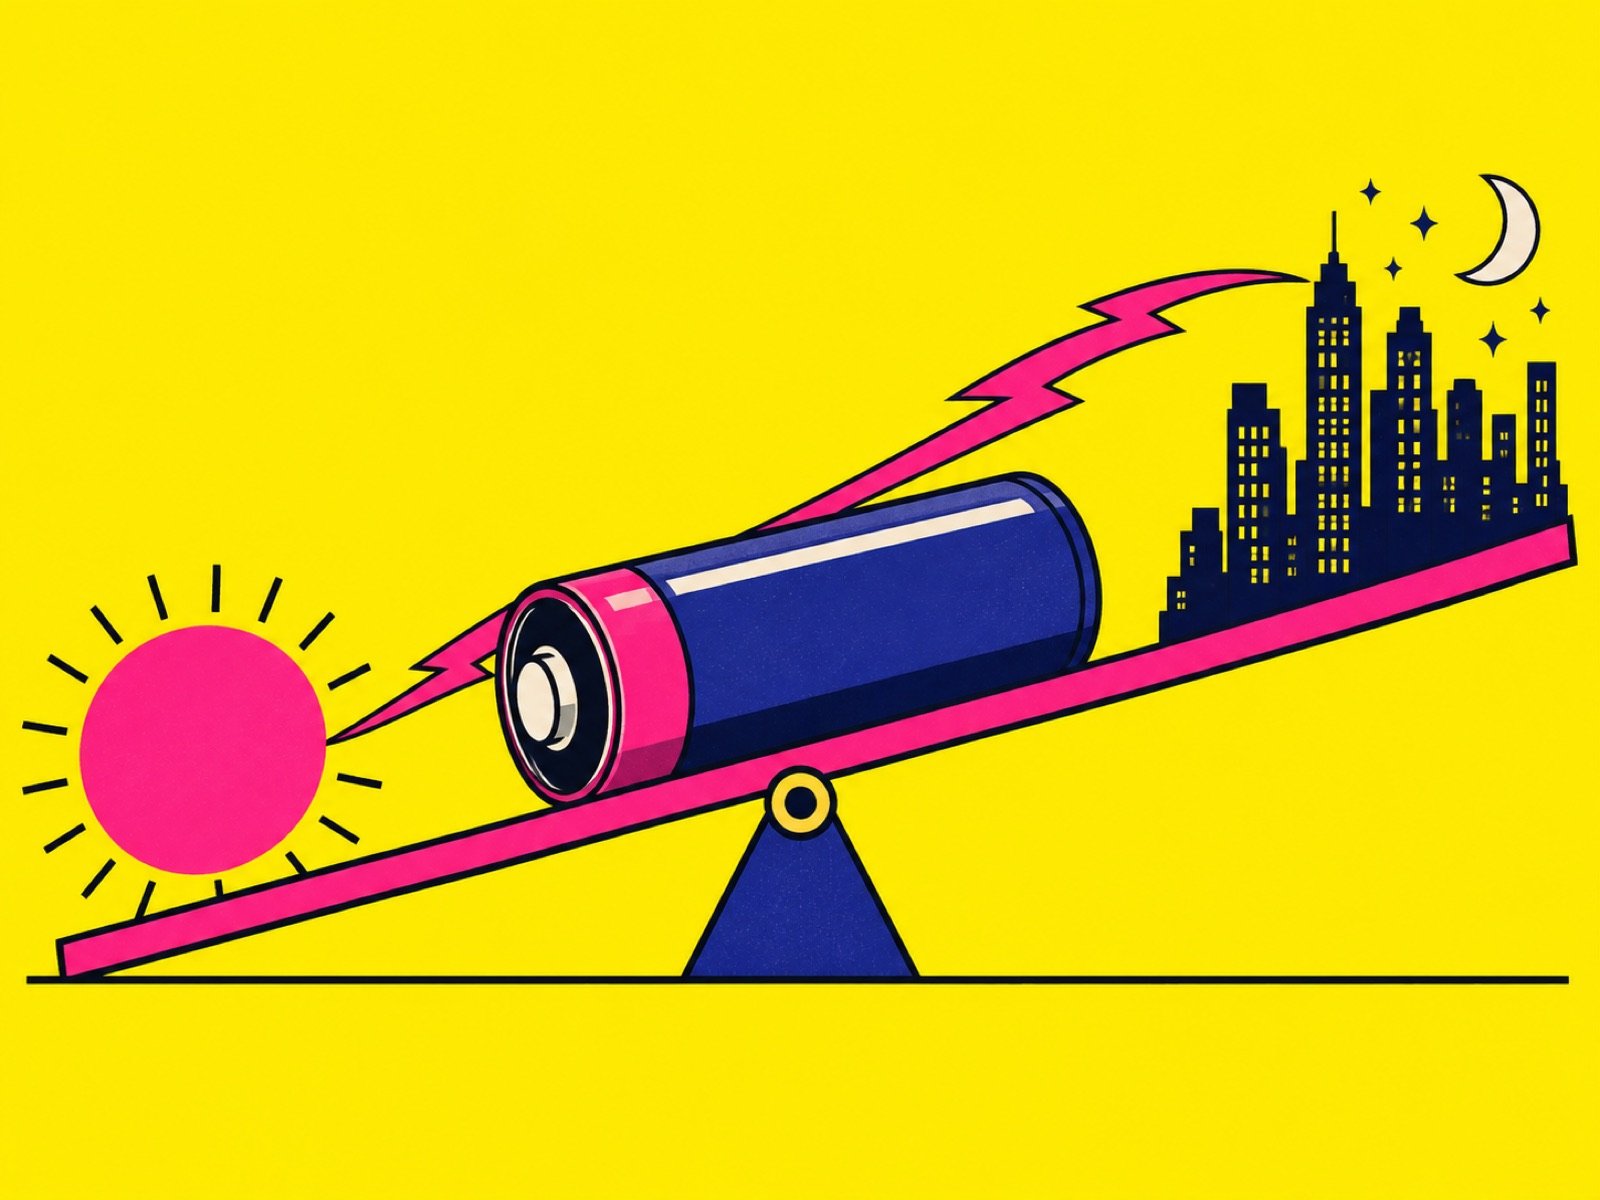
Two days with the same average electricity price can offer a battery very different earnings. A battery can earn revenue by buying in cheaper periods and selling in dearer ones; the gap between them matters. EEX’s 2026 top-to-bottom power futures turn that within-day spread into a standardised financial contract.
The exchange’s September presentation sets out the new product range, while its October 2 contract specifications define the settlement calculation. The contracts measure a spread within the day-ahead market. Storage operators can compare that common reference with the prices their own assets can capture, after accounting for the constraints on dispatch.
A conventional exposure to the general level of electricity prices need not resemble a storage business. A battery buying and selling within a day can be hurt when expensive and cheap periods move closer together, even if the average price rises. Conversely, wider differences may create opportunity without any rise in the average.
EEX’s product explanation links the need for a new hedge to changing intraday patterns as renewable generation grows. Solar output, for example, can make the middle of a day behave differently from morning or evening. The exchange presents this as a reason to hedge changing price patterns, without assuming that each day follows the same pattern.
For the continental two-hour profile, known as TB2, the settlement measure takes the average price of the eight highest-priced quarter-hours and subtracts the average of the eight lowest. These periods need not be consecutive. The four-hour profile uses sixteen quarter-hours on each side. The final reference is the average of the daily spreads over the delivery period. Great Britain’s TB2 specification instead uses the two highest and two lowest hourly periods until a move to quarter-hour intervals.
The calculation selects periods after observing all the prices. It gives counterparties a repeatable measure, but makes no allowance for whether a battery could have charged and discharged in that order.
A real installation cannot treat every cheap and expensive period as independently available. It has a finite state of charge. Some electricity is lost in charging and discharging. Power limits constrain how quickly energy moves, while maintenance or a network restriction may prevent dispatch at an otherwise attractive time.
The order of prices matters too. A high-priced period early in the day is useful only if the battery has energy available then. Counting the day’s most attractive prices without modelling that sequence abstracts from a decision an operator must actually make. Two installations facing identical prices can capture different earnings because they enter those periods with different amounts of stored energy.
EEX explicitly presents the benchmark as price-only, excluding assumptions about degradation, cycling constraints and dispatch models. A shared reference can bring different counterparties into the same contract instead of giving each asset a separate bespoke formula. The trade-off is the difference between the benchmark and the exposure of an individual project, often called basis risk.
Cash settlement means a derivatives position does not itself schedule a battery or deliver electricity. It can change the financial consequences of a movement in the reference spread. The hedge’s usefulness depends on how closely the project’s earnings move with the reference spread. Dispatch results show the revenue actually captured; the futures settlement records the benchmark movement.
There is also a collateral budget. European Commodity Clearing’s margin methodology describes initial margin as protection against potential changes during the time needed to close out a position. It updates risk parameters daily and can add charges where concentration lengthens liquidation. A business cannot evaluate a cleared hedge solely by its eventual economic offset; the resources required to maintain the position matter as well.
Whether the contracts become cheap to trade depends on participation, quoted spreads and available size; the specifications establish none of those outcomes. Even with ample liquidity, a storage operator would retain the difference between the settlement formula and its own achievable dispatch. A hedge tied to the day’s best prices can offset part of the revenue risk while leaving the battery’s physical constraints untouched.
Same-day SPX options averaged 3.2 million daily contracts in the third quarter. Their effect on the underlying market depends on dealers’ net positions and how those positions change.
USDA expects more cotton at the end of 2026/27 than it did a month ago. The stockpile would still shrink over the season, with Brazil projected to outship the United States.
The second US-index reconstitution of 2026 takes effect after the December 11 close. Ranking, initial membership lists and implementation create different trading decisions.